Mobile money travel does not exist in Africa
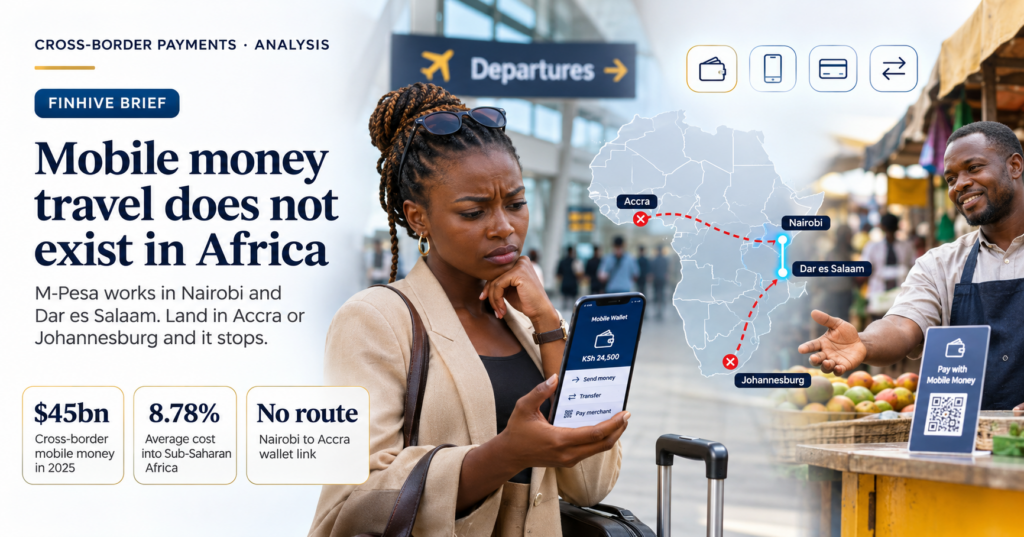
Your M-Pesa works in Nairobi and Dar es Salaam. Land in Accra or Johannesburg and it stops. Here is why, what banks solved decades ago, and how Africa fixes it.
Sources: World Bank RPW via SARB paper, EAC/World Bank via Bankable, GSMA State of the Industry 2026
The traveller test
Picture a Nairobi trader who flies to Accra to buy stock. A hotel takes Visa, so you pay with M-Pesa GlobalPay, a virtual Visa card linked to your wallet. Safaricom set a 3.5% FX fee at its 2022 launch.
Then you reach the market. The stall owner takes MTN MoMo. Your wallet cannot pay her. No published route links M-Pesa to MTN MoMo Ghana, in either direction.
Fly on to Johannesburg and it gets worse. Vodacom closed M-Pesa South Africa in 2016. MTN MoMo South Africa can send money to M-Pesa in Kenya and Tanzania. You cannot send it back.
| From | To | Status | Detail |
|---|---|---|---|
| NairobiM-Pesa Kenya | AccraMTN MoMo Ghana | No route | No wallet link found in either direction |
| Dar es SalaamM-Pesa Tanzania | AccraMTN MoMo Ghana | No route | M-Pesa Global (Nov 2025) names Uganda, China, Dubai. Not Ghana |
| NairobiM-Pesa Kenya | JohannesburgAny SA wallet | No route | M-Pesa South Africa closed in 2016 |
| JohannesburgMTN MoMo SA | Nairobi, DarM-Pesa | One way | 4% per send plus partner bank FX (Apr 2024) |
| AccraMTN MoMo Ghana | Any country | Not licensed | Bank of Ghana statement, Mar 2025 |
| NairobiM-Pesa Kenya | KampalaMTN Uganda | Send only | Safaricom corridor list |
| NairobiM-Pesa Kenya | Kigali, DarMTN Rwanda, Vodacom TZ | Open | Send and receive. FX rate shown only at confirmation |
| AnywhereM-Pesa virtual card | Visa merchants | Card only | Works where Visa works. Market stalls and taxis stay out of reach |
Sources: Safaricom IMT FAQ (accessed Oct 2026), TechCabal Nov 2025, IT Edge News Apr 2024, Graphic Online Mar 2025, News24 May 2016, Business Daily Jun 2022.
The price of the gap
When wallets cannot connect, you fall back on banks, money transfer operators and cash. In Sub-Saharan Africa, banks averaged 16.7% on a $200 send in Q1 2025. Money transfer operators averaged 7.5%.
Look closely at the cost and one item dominates. The FX margin is the cost. On Tanzania to Kenya by mobile money, the send fee was 1.03%. The FX margin was 15.37%. Rwanda to Kenya has M-Pesa and MTN links, yet the corridor still averaged 17.7%.
Sources: World Bank Remittance Prices Worldwide via SARB paper (Q1 2025), EAC release via Bankable (Jun 2025)
Five barriers keep wallets at home
- Licences stop at the border. E-money licences are national. Passporting exists only inside the two CFA franc zones. Nigeria limits money transfer operators to inbound transfers paid in naira.
- FX is the cost. Each currency swap adds a margin. Each aggregator hop adds another.
- Dominant wallets guard their networks. A June 2026 Kenya Bankers Association paper says big providers may lack the incentive to open up. Airtel opened its tills to M-Pesa users only in March 2025.
- No shared rules. No published cross-border mobile money dispute rulebook exists anywhere in Africa.
- Data rules block screening. 24% of mobile money providers named cross-border data rules as their top regulatory obstacle in 2025.
Technology ranks last. The pipes can be built. The rules and the currency problem stay unsolved.
What banks got right
Your Kenyan Visa card works in a Johannesburg shop. The reason is four agreements. Mobile money has built the message links. It has not written these agreements.
One rulebook
Every issuer and acquirer signs the same rules. Liability is clear before the first payment.
Interchange
A set fee pays the provider whose customer or agent does the work.
Central bank settlement
A settlement bank sits underneath. Every side gets paid in trusted money.
Dispute rules
Chargebacks settle fraud and errors by a set process.
Sources: SARB Position Paper 02/2022, GSMA interoperability study, AfricaNenda SIIPS 2025
The operators know this. Their own answer to cross-border spending is to borrow a card network. M-Pesa has GlobalPay with Visa. In February 2024 MTN agreed with Mastercard to add a companion card to MoMo wallets in 13 markets.
Shared switches work at home
Inside each country, the fix is proven. Central banks that run one neutral switch, and make every provider join, see volumes climb fast.
Sources: TechCabal Aug 2025, AfricaNenda SIIPS 2025 Egypt case study, MicroSave Jun 2020
Where wallets already cross borders
Wallets travel today in two places only. Both use one currency and one rulebook. In West Africa, Orange Money, MTN, Moov and Wave sit on the BCEAO’s PI-SPI. In Central Africa, GIMACPAY links 11 mobile money operators and 53 banks. Everywhere else, regional rails serve banks first.
| Rail | Coverage | Mobile money | Latest status |
|---|---|---|---|
| PI-SPI | WAEMU, 8 states, one currency | Direct | Live since 30 Sep 2025. 175 participants authorised by 30 Sep 2026. No volumes published |
| GIMACPAY | CEMAC, 6 states, one currency | Direct | 12m+ transactions, XAF 601.7bn in 2023. Mobile money made up 73% of volume |
| PAPSS | Continental | Pilot | 13 countries with live participants (Jun 2026). Ghana to Nigeria wallet corridor via Onafriq in pilot |
| COMESA DRPP | COMESA | Trial | Launched Oct 2025. User trials in Malawi and Zambia. No volumes published |
| EAC switch | East African Community | Planned | Link national switches by 2028, one regional switch by 2030. Rwanda and Tanzania link in proof of concept |
| Ghana and Rwanda | Bilateral, East and West | Pilot | Announced Oct 2026. Bank and wallet links plus a licence passporting framework |
| TCIB | SADC | Not connected | 8 scheme participants. ZAR 324m settled in Jun 2026 |
| EAPS | Kenya, Uganda, Tanzania, Rwanda | Not connected | Bank-only. USD 2.0bn in the year to Jun 2024 |
Sources: Financial Afrik Oct 2026, Business in Cameroon, PAPSS coverage sheet Jun 2026, TechCabal Oct 2025, Bankable Jun 2025, GNA Oct 2026, SARB Jun 2026, The EastAfrican
How Africa fixes it
Every fix below has worked somewhere on the continent, or sits in a live pilot. Here is who should act, and how.
- Make every wallet join a neutral national switch.Proof: TIPS in Tanzania. The BCEAO mandate brought Wave onto PI-SPI.
- Accept each other’s KYC through tiered checks.Benin, Ghana and Rwanda ran a Smart Africa ID pilot in Oct 2026.
- Require the full FX cost on screen before you confirm.
- Allow capped outbound wallet corridors that settle in local currency.Nigeria approved the Onafriq and PAPSS naira pilot to Ghana.
- Join shared switches and regional rails. Keep bilateral links as backup.
- Publish your FX rate and fee up front.
- Share agents on a fee split.Proof: Uganda’s 70/30 model.
- Build the missing corridors through licensed hubs.Vodacom Tanzania reached China and Dubai through Thunes and TerraPay.
- Act as FX and settlement agent for wallet corridors.Ghana’s 2025 rules route remittance settlement through local banks.
- Sponsor wallets into PAPSS and TCIB where operators cannot join directly.
- Give non-banks a real seat in bank-owned switches such as PesaLink.
- Run neutral hubs that issuers do not own.
- Settle corridors through PAPSS in local currency.
- Build cross-border account lookup and confirmation of payee.
- Use ISO 20022 and open standards.Rwanda and Liberia went live on Mojaloop in 2025.
- Hit the EAC 2028 switch target and put wallets in from day one.
- Write one regional rulebook for interchange, liability, disputes and FX.
- Recognise each other’s licences, as WAEMU and CEMAC already do.
- Make published volumes a condition of membership. PAPSS, PI-SPI and the COMESA platform publish none today.
A roadmap to 2030
Fix the home market
- Kenya passes its National Payment System Bill and brings M-Pesa onto a shared switch
- Ghana to Nigeria wallet corridor leaves pilot
- Rwanda and Tanzania switch link goes live
- Travellers keep using virtual cards
Link the switches
- EAC interconnects national switches, its stated target
- Ghana and Rwanda link extends to Kenya and Tanzania
- Regional rulebook and licence recognition adopted
Connect the regions
- EAC launches one regional switch, its 2030 target
- PAPSS links PI-SPI, GIMACPAY, TCIB and COMESA with wallets on board
- Local-currency FX replaces USD routing
Only the EAC 2028 and 2030 dates come from an official plan. The rest are FinHive proposals.
Three tests to watch
- GH ↔ NGThe PAPSS wallet corridor via Onafriq. If it scales, wallets can settle across currencies without USD.
- RW ↔ TZThe switch link in proof of concept since Nov 2025. It is drafting the dispute and pricing rules Africa lacks.
- GH ↔ RWThe first announced East to West link that includes wallets. The shortest route to M-Pesa in Accra runs through Kigali.
What would it take to make your M-Pesa work in Accra?
Tell us which fix should come first: regulators, operators or banks. We read every reply.