The Man Behind Your M-Shwari Loan Is Moving to Johannesburg
Absa Group has hired Eric Muriuki, one of Africa’s most decorated digital banking builders, from NCBA. This is the story of the products he built, the people he raised, and what his exit means for Kenya.
Think back to the first time you saved money on your phone.
Maybe it was KSh 100 tucked into M-Shwari after a good week. Maybe it was a midnight emergency, and an M-Shwari loan landed before you put the phone down.
Or maybe it was last Tuesday. Your M-Pesa balance read KSh 40. The matatu fare was KSh 80. Fuliza covered the gap, and you got home.
You never met the man behind those moments. Most Kenyans never did.
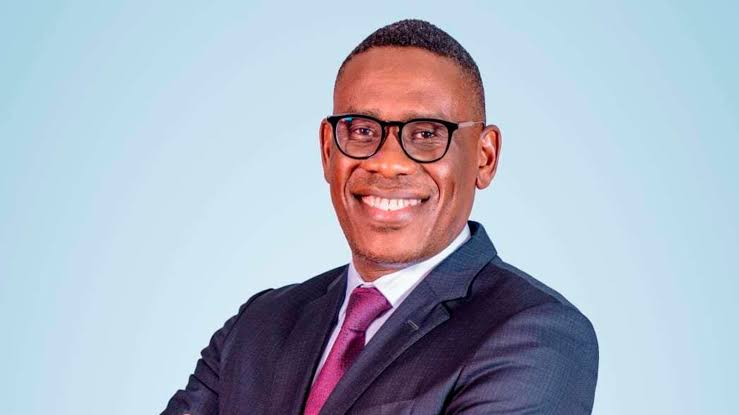
His name is Eric Muriuki. And as of this week, he works for Absa Group in Johannesburg.
Absa has appointed Muriuki as Managing Executive, Pan-African Growth Strategy, Platforms and Digital Ventures. From Johannesburg, he will lead the group’s regional growth agenda, its digital platforms and its new ventures across its African markets.
He leaves NCBA Group after 19 years. His last roles there were Group Director of Digital Business and CEO of LOOP Digital Financial Services.
Put simply, Absa just hired one of the most decorated digital banking executives in Africa away from NCBA.
To see why that matters, you have to go back to 2007.
27 years, one thread
Career timeline- 1999Citi, Business Systems ManagerGraduates from JKUAT in Mathematics and Computer Science
- 2004Co-operative Bank, Business Change Manager
- 2007Joins CBA. Helps design the M-Pesa trust-account frameworkThe settlement model behind mobile money
- 2008MBA in Strategy, Strathmore Business School
- 2012GM, New Business Ventures. M-Shwari launchesSavings and micro-credit on any phone
- 2014M-Pawa with Vodacom TanzaniaThe model goes regional, MTN’s MoKash and MoMoKash follow
- 2017Loop launchesA full bank on your phone, no banking hall
- 2019Fuliza launches. Becomes CEO of LOOP DFS
- 2026Absa Group, JohannesburgManaging Executive, Pan-African Growth Strategy, Platforms and Digital Ventures
Source: Pulse Kenya, Capital FM, TechCabal.
2007The rules that made mobile money safe
In 2007, M-Pesa was brand new. It raised a hard question. When a telco holds your money as electronic value, who protects it?
Muriuki had just joined Commercial Bank of Africa as Programme Director for Enterprise Transformation. He helped design the answer: the trust-account structure that allowed Safaricom to issue electronic value with regulatory approval.
The idea is simple. Every shilling in your M-Pesa wallet is backed by real money held in trust at banks. The telco runs the service. The banks hold the funds. The regulator can sleep at night.
That settlement architecture became the blueprint for how telcos and banks share the mobile money business. Operators across Africa have used it as a reference model when they launch their own mobile money services.
You will never see it on your phone screen. Every M-Pesa transaction still runs on it.
2012A bank account on a kabambe phone
His next big idea took shape in a classroom. During his MBA studies at Strathmore Business School, he chased a question that would define his career. Could a bank lend to someone with no payslip, no collateral and no time to queue at a branch?
In November 2012, CBA and Safaricom answered with M-Shwari. You could save and borrow from a basic phone, with your M-Pesa history standing in for a title deed.
It ranks among the first mobile savings and micro-credit platforms in the world. M-Shwari has now served more than 30 million customers and disbursed over US$6 billion in loans.
For a mama mboga in Kawangware or a boda rider in Eldoret, that meant something no bank had offered them before. A credit history. A safety net. A chance.
2014 onwardA Kenyan idea crosses borders
M-Shwari worked. So Muriuki and his team packed the model and took it to new markets.
In 2014, CBA partnered with Vodacom to launch M-Pawa in Tanzania. MTN followed with MoKash in Uganda and Rwanda, and MoMoKash in Côte d’Ivoire. Each launch paired the bank with a major mobile operator to build savings and lending together.
Together, these platforms have reached a combined 35 million customers and disbursed more than US$2 billion in loans.
The industry now calls this the mobile savings and lending model, or MSL. Banks and telcos across Africa study it when they design their own products.
One model, six markets
Bank + telco partnershipsSource: Business Daily Africa, AllAfrica, TechCabal. Customer figures as last reported by NCBA.
2017Loop, the bank with no banking hall
By 2017, Muriuki was General Manager for New Business Ventures. He wanted to build something bolder: a complete bank that lived on your phone.
CBA launched Loop in March 2017. Young Kenyans could open an account, get a card, pay bills and send money without stepping into a branch.
“The banking model is broken and we want to change that.”
Eric Muriuki, at the launch of Loop, Daily Nation
Loop launched as the first digital bank of its kind in Kenya and the region. From 2019, Muriuki led it as CEO of LOOP DFS, NCBA’s digital-first business for young professionals, merchants and entrepreneurs.
2019Fuliza and the end of “insufficient funds”
In January 2019, Safaricom launched Fuliza with its partner banks, CBA among them. Muriuki helped co-create it.
Fuliza fixed a daily pain. Your balance falls short. The payment goes through anyway. You repay when money comes in.
Today Fuliza processes more than four million transactions every day. It has provided over US$25 billion in short-term liquidity.
That is a lot of school fees, fuel, medicine and unga paid on time.
The scale of what he helped build
By the numbersMoney moved to customers, lifetime (US$)
Source: AllAfrica (July 2026), Business Daily Africa, Nedbank Group, Pulse Kenya.
The proof is on the balance sheet
These products changed NCBA itself. In 2025, digital loans delivered 31.9% of the group’s pre-tax profit. The digital business, led by Muriuki and his teams, grew into the engine of one of East Africa’s biggest banks.
Then came the clearest proof of value. In 2026, South Africa’s Nedbank agreed to buy a 66% stake in NCBA for R13.9 billion, about US$842 million. Reports on the deal pointed to Nedbank’s plan to take NCBA’s Loop platform beyond East Africa, South Africa included.
Sit with that for a moment.
The people he raised
Products tell half of Muriuki’s story. People tell the other half.
He has closely mentored more than 20 executives who came through LOOP DFS. Many now hold senior roles in digital finance across Africa, Europe, the United States and Asia.
Ask around Nairobi’s fintech circles and you will meet them. Product heads. Chief digital officers. Founders. Thought leaders. Many of them learned the craft on his teams.
That may be his most lasting product. It never shows up on a balance sheet, yet it keeps compounding.
The “Avengers” are assembling at Absa
Muriuki will not be the only Kenyan mobile money pioneer in Absa’s leadership.
In February, Absa named Sitoyo Lopokoiyit, then Managing Director of M-Pesa Africa, as Chief Executive, Personal and Private Banking. He took up the role on 1 April 2026.
One spent years scaling M-Pesa from the telco side. The other built mobile banking from the bank side. Now they sit in the same group, in the same city.
Absa’s Kenyan digital bench, 2026
Two hires, one playbookSource: Absa Group announcements via Citizen Digital, The Star and Pulse Kenya.
What FinHive will watch next
- Telco partnerships. Absa now holds two leaders who know the bank and telco playbook from both sides. Expect conversations with mobile operators in Absa’s markets.
- New digital ventures. The words “Digital Ventures” in his title point to standalone businesses, built to scale beyond Absa’s existing customer base.
- The talent pull. Strong leaders attract their former teams. Watch for more Nairobi digital finance talent heading south.
- NCBA’s next chapter. Nedbank’s ownership and a new LOOP leader will shape how NCBA defends the business Muriuki built.
What Kenya loses
This move stings a little.
Kenya showed the world how mobile money and mobile credit can work. The pioneers who made it happen are now in demand everywhere, and bigger institutions abroad are winning them.
Each exit carries years of hard-won knowledge out of the country. How to negotiate with a telco. How to price risk for a customer with a basic phone. How to serve millions without a single branch.
So here is a question for Kenyan banks, telcos and regulators. Who is the next Eric Muriuki, and what are you doing today to keep them?
Muriuki is a rare kind of leader. He understands the customer, the business, the product and the technology. Few executives master all four.
He started out as a mathematics and computer science graduate from JKUAT. He leaves Kenya as one of the architects of how a continent saves, borrows and pays.
The next time Fuliza rescues your evening, or M-Shwari covers an emergency, you will know whose thinking sits behind it.
Kwaheri, Eric. Kenya will miss you. Africa gets to keep you.
All the best in Johannesburg.
Sources
- Pulse Kenya: Absa Group appoints Eric Muriuki (7 Oct 2026)
- AllAfrica: NCBA deepens digital banking push (Jul 2026)
- Business Daily Africa: NCBA mints 32pc of profit from Fuliza, M-Shwari loans
- Nedbank Group: Intention to acquire majority stake in NCBA
- Daba Finance: Nedbank bets $842M on NCBA
- Citizen Digital: Sitoyo Lopokoiyit joins Absa
- Daily Nation: CBA eyes youth with digital platform
- TechCabal: Fuliza, M-Shwari push NCBA’s digital lending past $7.7 billion